
Retail fraud protection isn’t just a merchant problem anymore. Fraudsters cost businesses billions each year, but the wrong fix — blocking too many orders — can cost you loyal customers too. This guide shows you how to stop real fraud without turning away real shoppers.
What Retail Fraud Protection Actually Means
Detection and protection aren’t the same thing. Detection flags suspicious activity. Protection stops the loss and keeps a good customer checking out at the same time.
Most fraud tools do one job well and fail at the other. A rule that blocks stolen cards often blocks travelers, new movers, and anyone paying with an unfamiliar address. That’s not protection. That’s a different kind of loss.
Retail fraud protection covers three groups:
- Merchants, who need fewer chargebacks without fewer sales
- Marketplaces, managing risk across thousands of third-party sellers
- Shoppers, who want their card details and accounts kept safe
This guide speaks to all three.
The Real Cost of Retail Fraud
A $50 fraudulent order rarely costs $50. LexisNexis Risk Solutions found merchants lose an average of $4.61 for every $1 of fraud once you count lost goods, shipping, chargeback fees, and staff time reviewing the case.
LexisNexis Risk Solutions fraud cost study
Run that math on 100 fraudulent orders a month and the number stops looking small.
But there’s a second cost most dashboards miss: false declines. Block a legitimate customer once and many won’t come back. That single bad experience can end a relationship worth hundreds of dollars over time.
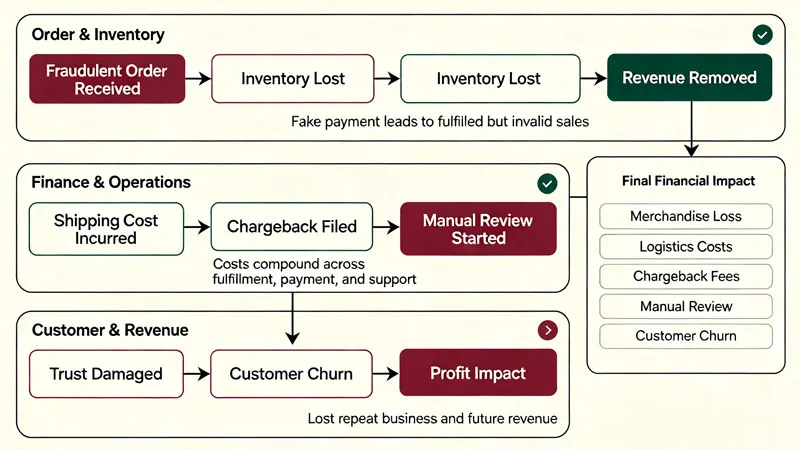
The takeaway: a fraud strategy that only counts blocked fraud is measuring half the problem.
Types of Retail Fraud You Need to Recognize
Card-Not-Present (CNP) Fraud
A stolen card number, used online with no physical card to check. This is still the most common type of payment fraud retailers face.
Account Takeover Fraud
Someone logs into a real customer’s account using stolen credentials, then spends their saved payment method or loyalty points.
First-Party (Friendly) Fraud
The customer is real. The purchase is real. But they dispute the charge anyway, often claiming the item never arrived.
Return and Refund Abuse
Wardrobing, fake receipts, and “empty box” claims all fall here. Loose return policies make this one worse.
Promo and Coupon Abuse
Multiple fake accounts, one goal: claim the same discount over and over.
AI Agent Takeover Fraud
This one is new. As shoppers hand purchasing tasks to AI agents, fraudsters are starting to hijack those agents’ stored credentials and permissions to place unauthorized orders. Expect this threat to grow fast through 2026 as agentic commerce scales.
| Fraud Type | Business Risk | Shopper Warning Sign |
|---|---|---|
| CNP fraud | Chargebacks, lost goods | Unrecognized charges on statement |
| Account takeover | Loyalty point theft, data exposure | Login alert you didn’t trigger |
| Friendly fraud | Revenue loss, merchant account risk | N/A (customer-initiated) |
| Return abuse | Inventory loss, restocking cost | N/A (fraudster-initiated) |
| AI agent takeover | Unauthorized bulk orders | Orders you didn’t approve via your agent |
Building a Retail Fraud Protection Strategy
Strong protection works in layers. No single rule catches everything.
Checkout-level verification. Address Verification Service (AVS), CVV checks, and 3D Secure 2.0 catch a large share of stolen-card attempts before they process.
Behavioral signals. Device fingerprinting and typing patterns flag accounts that don’t behave like the real owner, even when the login credentials check out.
Seasonal and SKU-level modeling. Fraud spikes around high-demand product launches and holidays. A model trained on your product mix catches patterns a generic tool misses.
Compliance from day one. Any fraud tool touching customer payment data needs to meet PCI DSS standards. If you operate in the EU or serve EU customers, GDPR governs how you store and process that fraud-related data too.
PCI Security Standards Council compliance requirements
| Generic Fraud Tools | Retail-Specific Protection | |
|---|---|---|
| Data source | General transaction history | SKU-level, seasonal, retail behavior |
| False decline rate | Higher | Lower |
| Chargeback liability | Usually stays with merchant | Often shifted to provider |
| Compliance coverage | Varies | Built for retail regulations |
Retail Fraud Protection for Small Businesses
Enterprise tools aren’t the only option. Most payment processors now build fraud protection into their core product.
- Stripe Radar and PayPal Seller Protection flag risky transactions automatically at no extra setup cost.
- Shopify Protect covers eligible chargebacks on Shopify stores directly.
- A simple manual review process — checking billing-shipping mismatches and order velocity by hand — still works for stores under a few hundred orders a month.
Outsourcing makes sense once manual review starts eating into time you’d rather spend on growth. That’s usually somewhere past 500-1,000 orders a month, depending on your team size.
small business chargeback prevention tools
How to Choose a Retail Fraud Protection Provider
Run any provider through this checklist before you sign:
- Approval rate impact. Ask for real before-and-after numbers from existing customers, not projections.
- Liability shift. Does the provider guarantee approved orders, or does the chargeback risk stay with you?
- Compliance coverage. PCI DSS is table stakes. Ask about GDPR and CCPA handling too.
- Integration time. Some platforms plug in within days. Others need months of engineering work.
- Pricing model. Per-transaction fees add up fast at scale. Flat-rate models suit high-volume stores better.
No provider blocks 100% of fraud. Anyone promising that number isn’t being straight with you.
How Shoppers Can Protect Themselves
Retail fraud protection isn’t only a business problem. Shoppers carry risk too.
- Check for HTTPS and a real business address before entering card details on an unfamiliar site.
- Use a credit card, not a debit card, for online purchases. Credit cards offer stronger dispute rights under federal law.
- If your account gets locked after a legitimate purchase, contact support directly and ask for a security team escalation. Most reputable retailers can verify your identity within 24-48 hours.
- Watch for triangulation scams: unusually low prices on a site you’ve never heard of, paired with vague seller information, is a common setup for stolen-card fulfillment schemes.
Federal Trade Consumer Protection guidance
How to dispute a fraudulent charge
What’s Next for Retail Fraud Protection
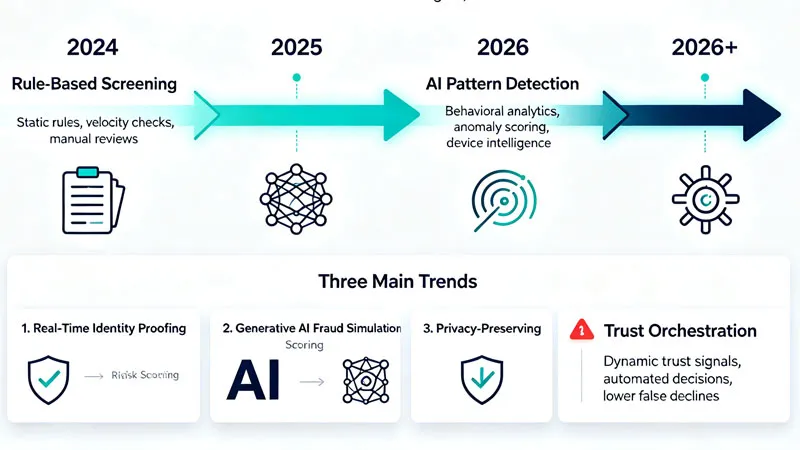
Three shifts are worth watching through the rest of 2026:
- Agentic commerce will keep expanding the attack surface as more shoppers delegate purchases to AI tools.
- Consortium data — fraud signals shared across merchants — will keep improving detection accuracy without slowing down checkout.
- Card network rules on liability and dispute handling continue to shift, often favoring stronger merchant protections when verification steps are followed correctly.
FAQ: Retail Fraud Protection
Is retail fraud protection the same as chargeback protection?
No. Chargeback protection covers disputes after the fact. Fraud protection stops the bad order before it ships.
How much does retail fraud protection cost a business?
Pricing varies widely — from free built-in processor tools to per-transaction fees of 1-3% for dedicated providers. Cost depends on order volume and risk level.
Can any tool guarantee zero fraud losses?
No. Even the best systems trade off some risk. The goal is minimizing losses while approving as many good orders as possible.
What should I do if my legitimate order gets flagged as fraud?
Contact the retailer’s support team directly and ask for identity verification through their security team. Most resolve this within one to two business days.
Do small businesses need dedicated fraud protection tools?
Not always at first. Built-in tools from Stripe, PayPal, or Shopify cover most early-stage needs. Dedicated tools make sense once order volume makes manual review impractical.
Disclaimer: This article is for informational purposes only and does not constitute financial, legal, or investment advice. Fraud prevention needs vary by business and jurisdiction. Consult a licensed compliance professional or attorney before implementing a fraud protection strategy.